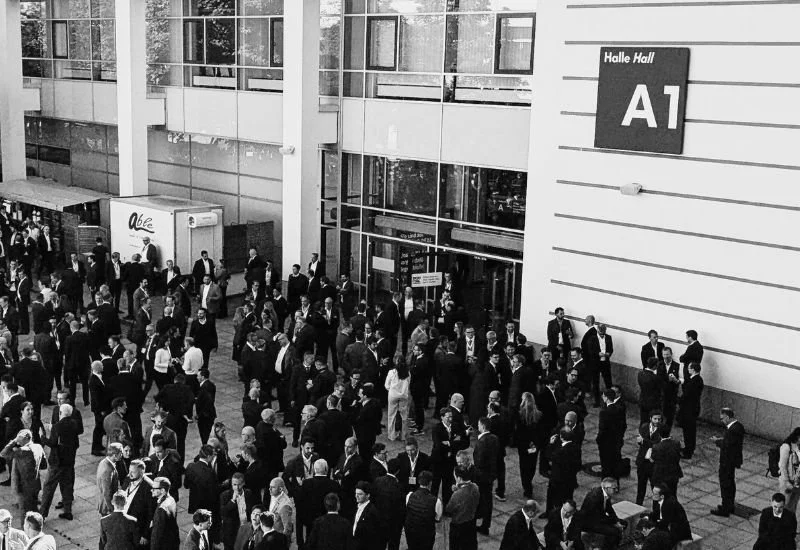
Last week, our team spent two days on the floor at Expo Real in Munich. The market looked in reasonable shape on the surface, with deals being discussed and confident conversations. What interested us more, though, was what sat underneath that mood.
Two themes kept coming up: who is buying the firms that manage and advise on property, and how loosely AI is being governed. Neither dominated the headlines or the panel discussions we attended, but both matter to anyone who runs buildings or invests in them, whatever the sector.
Private equity is setting the price
Property services firms looking to grow in Europe are now frequently bidding against private equity, which can pay more for the same business. On day one, we heard this described as one of the reasons organic growth has become so difficult. On day two, there was talk of further deals and rumours of others.
Some firms are taking the longer view and choosing to remain independent. But they are doing so in a market where buyers are well funded and, on paper at least, the deals can look very sensible to sellers.
It would be easy to shrug at this. A well-priced acquisition rarely looks like a problem in isolation. Our concern is the pattern.
Mid-size firms hold much of the sector's expertise and local knowledge, and they train many of its future leaders. If private equity continues acquiring these businesses and selling them on, the long-term outlook for the mid-size tier becomes more difficult.
Collectively, we're old enough to have seen what can follow. Fewer firms mean less competition. Less competition puts pressure on fees, and squeezed fees have a habit of being followed by slipping standards.
For property managers, that means a changing field of peers and competitors, and a harder choice between selling, partnering and staying independent. For asset managers and investors, there is a practical question: what happens to the service quality and cost of the managers you rely on if the market narrows?
AI: plenty of talk, thin governance
We went looking for inventive uses of AI and didn't find many. A few firms are using it in a coordinated way across their business, but more often it lives in pockets, with individual users getting real value while the rest of the organisation watches.
In most of our conversations, it became apparent that few, if any, guardrails were in place.
Our sector runs on records: leases, service charge budgets, performance reporting and compliance documents. If an AI tool misreads or misstates that data, the error doesn't stay put. It gets copied into reports, benchmarks and valuations, and from there into decisions. Once flawed output has been baked into shared records, it can be hard to find and slow to correct.
The question we'd put to any manager using AI is simple: who is accountable for the quality of the data it touches?
Clean data is the asset. Handing it to a tool without clear rules for checking its output puts that asset at risk. Governance, by which we mean clear ownership, human review of outputs and agreed data-quality standards before anything is automated, is the part most firms have yet to build.
Two notes from the floor
Hotels. One for the hospitality investors among you: European hotel occupancy is running at roughly 60 to 70 per cent, with an average room rate of about €113. Occupancy at that level is healthy, but the rate looks low enough to question whether it can last, with implications for investors and asset managers in the sector.
The robots. Expo Real is not short of spectacle. We watched a dancing robot and a humanoid so lifelike that it was slightly unsettling. Memorable, certainly, although neither came with a business case.
What we'll be watching
Over the next six to twelve months, these are the questions we'll be following:
Do management and advisory fees hold as the number of independent firms falls?
Do the firms that stay independent find ways to compete on service, or are they pushed to sell?
Does anyone put real AI governance in place before a high-profile data error forces the issue?
What will investors start to expect from their managers on data quality?
Most people we spoke to in Munich didn't seem worried about any of this. The ones who were had thought about it carefully.
If you were at Expo Real and saw things differently, or you're a property manager or asset manager weighing up what these changes mean for you, we'd like to hear from you. You can reach the team through our contact page.